Renewed tensions involving Iran have exposed vulnerabilities that many energy planners had hoped to manage through diversification. Although the immediate effects of a conflict may be geographically concentrated, energy markets respond to anticipated disruption as much as to actual shortages. Traders, governments, and industrial consumers therefore monitor military developments, shipping data, and diplomatic statements with unusual intensity.
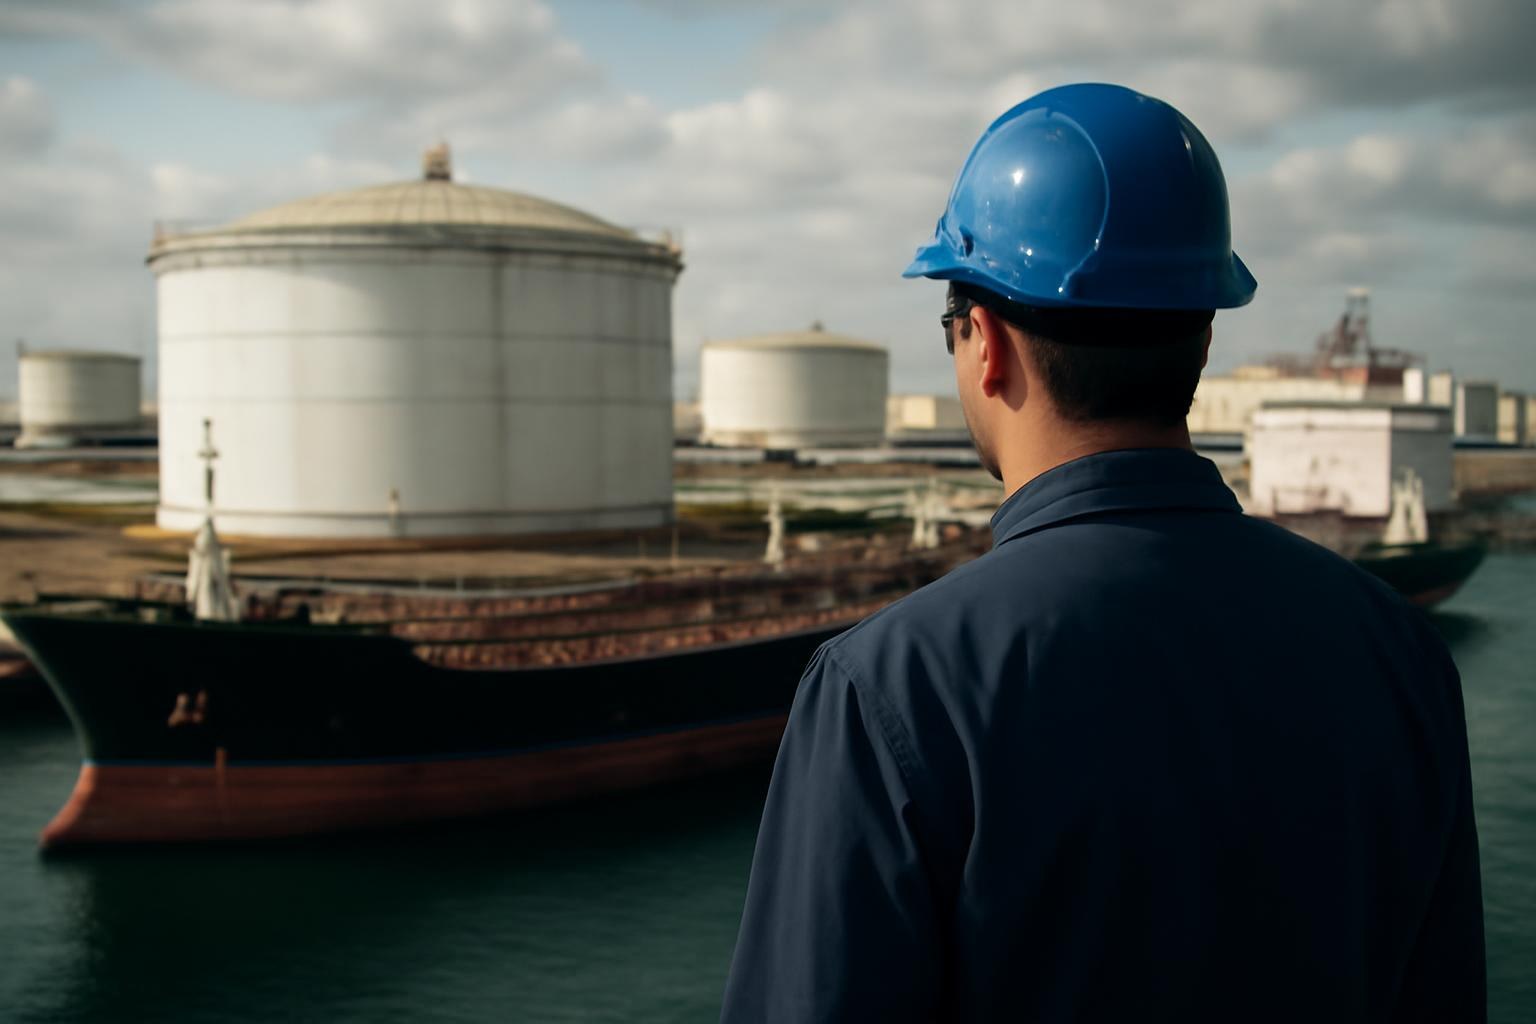
The most sensitive concern is the security of maritime corridors linking the Persian Gulf with international markets. A serious incident near a major shipping route could delay tankers, raise insurance premiums, and force vessels to take longer and more expensive paths. Even when navigation remains technically possible, uncertainty can reduce the volume of cargoes that companies are willing to dispatch.
Oil markets are particularly responsive because petroleum is traded globally and benchmark prices incorporate expectations about future supply. A temporary disruption can produce a sharp price spike if buyers fear that spare capacity will be insufficient. Higher prices then affect transportation, manufacturing, food distribution, and household budgets far beyond the region where the conflict began.
Natural gas faces a different but related set of risks. Liquefied natural gas cargoes can be redirected, yet terminals, pipelines, and regasification facilities impose physical limits on how quickly supplies can be replaced. Countries that rely heavily on imported gas may compete for the same cargoes, creating regional price disparities and placing additional pressure on electricity producers.
The conflict also highlights the strategic importance of energy infrastructure. Offshore platforms, export terminals, refineries, pipelines, and undersea cables can become targets or collateral damage during a crisis. An attack does not need to destroy a facility completely; temporary closures, technical inspections, or cyberattacks may be enough to interrupt flows and undermine confidence.
Governments are responding by reviewing emergency reserves, supplier agreements, and demand-management plans. Strategic stockpiles can cushion a short-term shock, but they cannot solve a prolonged crisis or compensate for inadequate refining capacity. Policymakers must also coordinate releases carefully, since an uncoordinated response may calm one market while intensifying anxiety in another.
In the longer term, the most durable lesson is that energy security cannot depend solely on military protection or additional fossil-fuel contracts. Renewable power, efficient grids, flexible storage, and regional interconnections can reduce exposure to imported fuels, although these systems require substantial investment and resilient supply chains of their own. The Iranian crisis therefore presents a difficult but valuable reminder: energy security is simultaneously a geopolitical, economic, technological, and climate challenge.